COVID-19 has become a major lynchpin in the debate about whether or not the Philippines should engage in corporate tax reform.
The tax reform bill, which is now called CITIRA, will have major implications on the future of SEZs in the Philippines.
For years, the Philippines struggled to reform its taxes to improve efficiency and simplicity.
The last major wave of tax reform in the Philippines had been the Tax Reform Act of 1997.
The 1997 tax reform law had cut tax rates, but created numerous exceptions and loopholes. For example, PEZA, which was only two years old at the time, enjoyed numerous highly favorable tax incentives.
Over time, the presence of tax loopholes became increasingly controversial.
Furthermore, neighboring countries had slowly cut their own tax rates. By 2017, the Philippines had a corporate tax rate of 30%, the highest in the ASEAN region.
The country also had other disadvantages that made it a less desirable location than its ASEAN neighbors. These included poor logistics infrastructure, high cost of electricity, and slow internet.
Supporters argued that tax reform would have several benefits:
- Closing loopholes would increase government revenue-Lowering taxes would make the Philippines more attractive when compared to its neighbors
- Business accounting and legal costs would be reduced due to a simplified tax code
In 2016, when Rodrigo Duterte ran to become President of the Philippines, he vowed to embark on a massive program of tax reform to make the Philippines more internationally competitive. Shortly after winning, he embarked on his project to reinvigorate the Filipino tax code.
The initial part of the tax reform package, called Tax Reform for Acceleration and Inclusion Act (TRAIN act) focused almost entirely on personal taxes. This passed in December 2017 with little controversy.
The second part of the tax reform package, now known as CITIRA, focused on corporate taxes. As part of the second wave of tax reform, the government planned to standardize and “flatten” incentives, to make them more uniform across the country.
This threatened the country’s economic zones in a number of significant ways. Notably, it threatened to transfer regulatory authority away from existing government agencies, make the areas outside of economic zones in the Philippines more tax competitive, and reduce the incentive that zones could provide to their tenants.
As a result, two political factions, respectively supporting or opposing corporate tax reform have emerged.
The first camp is led by the Department of Finance (DoF) and the Department of Trade and Industry (DTI). It is supported by a variety of industry and trade organizations such as banks, and real estate associations. It is also supported by Chinese special interest groups, as well as think tanks promoting free market economics.
Opposed to tax reform, is a loose coalition of diverse business interests. Most notably, as it relates to economic zones, is the Philippine Economic Zone Authority (PEZA). Also opposing tax reform are importer and exporter industry associations, the chambers of commerce of Western countries, and other zone operators and tenants.
Negotiations over corporate tax reform began in early 2018, and after extensive negotiations, came to a close in late 2019 when the DoF and DTI came to a tentative agreement with PEZA. However, this would not mark the end of negotiations.
The first COVID-19 cases were detected in the Philippines on January 31 2020, only weeks before the planned implementation date of the new tax reform package.
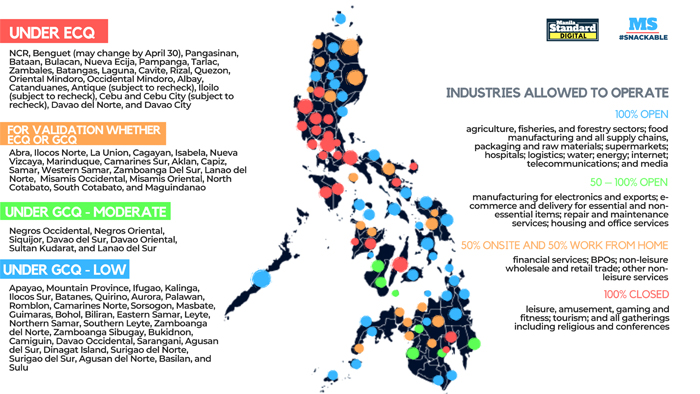
PEZA would withdraw from the negotiations, and argue that COVID justified a more favorable version of the tax reform legislation.
As a response, the supporters of the tax reform bill have also began incorporating COVID-19 into their arguments in favor of tax reform.
If the DoF and DTI succeed in using COVID-19 as a justification to pass corporate tax reform legislation, it could spell the end of Filipino economic zones. Conversely, if PEZA succeeds in using clauses within COVID-19 related economic legislation to covertly protect its incentives, it guarantees the survival of the program for years to come.